Everything before nine-thirty
S&P 500 7,637.76 · +85.95 · +1.14%
The S&P 500 rose 85.95 points on Thursday to 7,637.76, one and fourteen hundredths of one percent, the day after the Federal Open Market Committee raised interest rates for the first time since 2023. It was holding 79.63 of those points before the opening bell. The session that followed — six and a half hours, three hundred and ninety minutes of trading — produced the other 6.32. The index opened at 7,631.44, reached 7,646.60 inside its first ten minutes, and then spent the rest of the day failing to improve on that: the high of the whole session, printed at ten minutes to four, beat the high of the first ten minutes by twenty-six hundredths of one point. The low came at ten past ten and sat sixty points above Wednesday's close. The gap never filled, not by a point. There was no moment in the day at which yesterday's price was available to anybody.
The day's protagonist
Intel INTC
Move: +7.62% to $108.75, the largest move on the page
The day's engine was memory, and the man who started it does not sell any. Speaking at an industry event, Intel's chief executive Lip-Bu Tan said that demand for memory chips was not slowing and that prices would carry on rising — a remark about somebody else's product line that moved his own stock 7.62 percent and lifted the whole shelf with it. Micron rose 5.50, AMD 6.31, Broadcom 2.29, Nvidia 2.57, and the semiconductor fund 2.76. Technology finished at 2.26 percent, best of the eleven sectors by more than a point, and carried an index that would otherwise have had very little to show: strip the chips out of Thursday and the day is the Dow's 0.59 percent, not the Nasdaq's 1.72. It is worth setting that against the page before it. On Wednesday, with the Federal Reserve raising rates for the first time in three years, technology was also the best sector — at 0.13 percent, and one of only three green. The same shelf, one day apart, seventeen times the size. Nothing about the chips changed between Wednesday afternoon and Thursday morning except that somebody said out loud that prices were still going up, and that the rest of the market had decided overnight it could live with the Fed.
The deeper account
The two pages sit against each other so exactly that it is worth stating the pair before anything else. Wednesday was the FOMC decision, and its page is called "Nothing before two": at two o'clock the index had drawn 24.52 percent of its day's range, the lowest reading of the 133 sessions for which this site holds a complete intraday record, in a window where the median session has already made both its high and its low and gone quiet. Wednesday could not decide anything until the Fed spoke, and then moved 115 points in two hours. Thursday drew 99.17 percent of its range in the first forty minutes and then held a twenty-five-point band for the rest of the afternoon. One day could not begin until two in the afternoon; the next was finished by ten past ten in the morning. Between them sat a night, and the night did all the work.
What the reading in the coverage says is that Chairman Warsh's hawkishness restored the Fed's credibility on inflation, and that a market which sold the decision on Wednesday bought the credibility on Thursday. The cross-asset tape is consistent with that and unusually tidy about it: the ten-year came back under five percent, long Treasuries rose 1.11 percent, gold rose 1.67 and silver 3.35, and equities rose with all of them. Those four things do not normally move together. They do when what has changed is not the price of money but the market's confidence that somebody is minding it. Volatility fell 12.82 percent to a level below where it stood the Friday before the meeting, which is the same sentence said in a different unit.
The tape's own evidence, though, is narrower and harder than any of that, and it is the only thing on this page that is measured rather than reported: nobody changed their mind during trading hours. The conclusion was reached overnight, the price opened where the conclusion put it, and the session was six and a half hours long and moved the index 6.32 points. The first ten-minute bar of the morning found a high that six further hours could beat by twenty-six hundredths of a point. Whatever argument took place about the first rate rise in three years, it did not take place in the American stock market on Thursday. It had finished before the bell, somewhere else, among people who were not trading.
There is one loose thread and the page would rather name it than tidy it. Nine of the eleven sectors closed green and the two that did not are both places where borrowing lives — financials and communication services. But financials fell without its banks falling, and communication services fell 0.59 percent while Meta and Alphabet both rose more than 1.3 percent, because the telephone companies were sold hard: T-Mobile 5.57, Comcast 3.41, Verizon 2.86, AT&T 1.84. The explanation in print is rate sensitivity on indebted balance sheets. It does not survive contact with the rest of the same session, in which utilities — as indebted and as rate-sensitive as any carrier — rose 0.86 percent, and in which long bonds rallied. Something sold the carriers on Thursday and this page has not found out what.
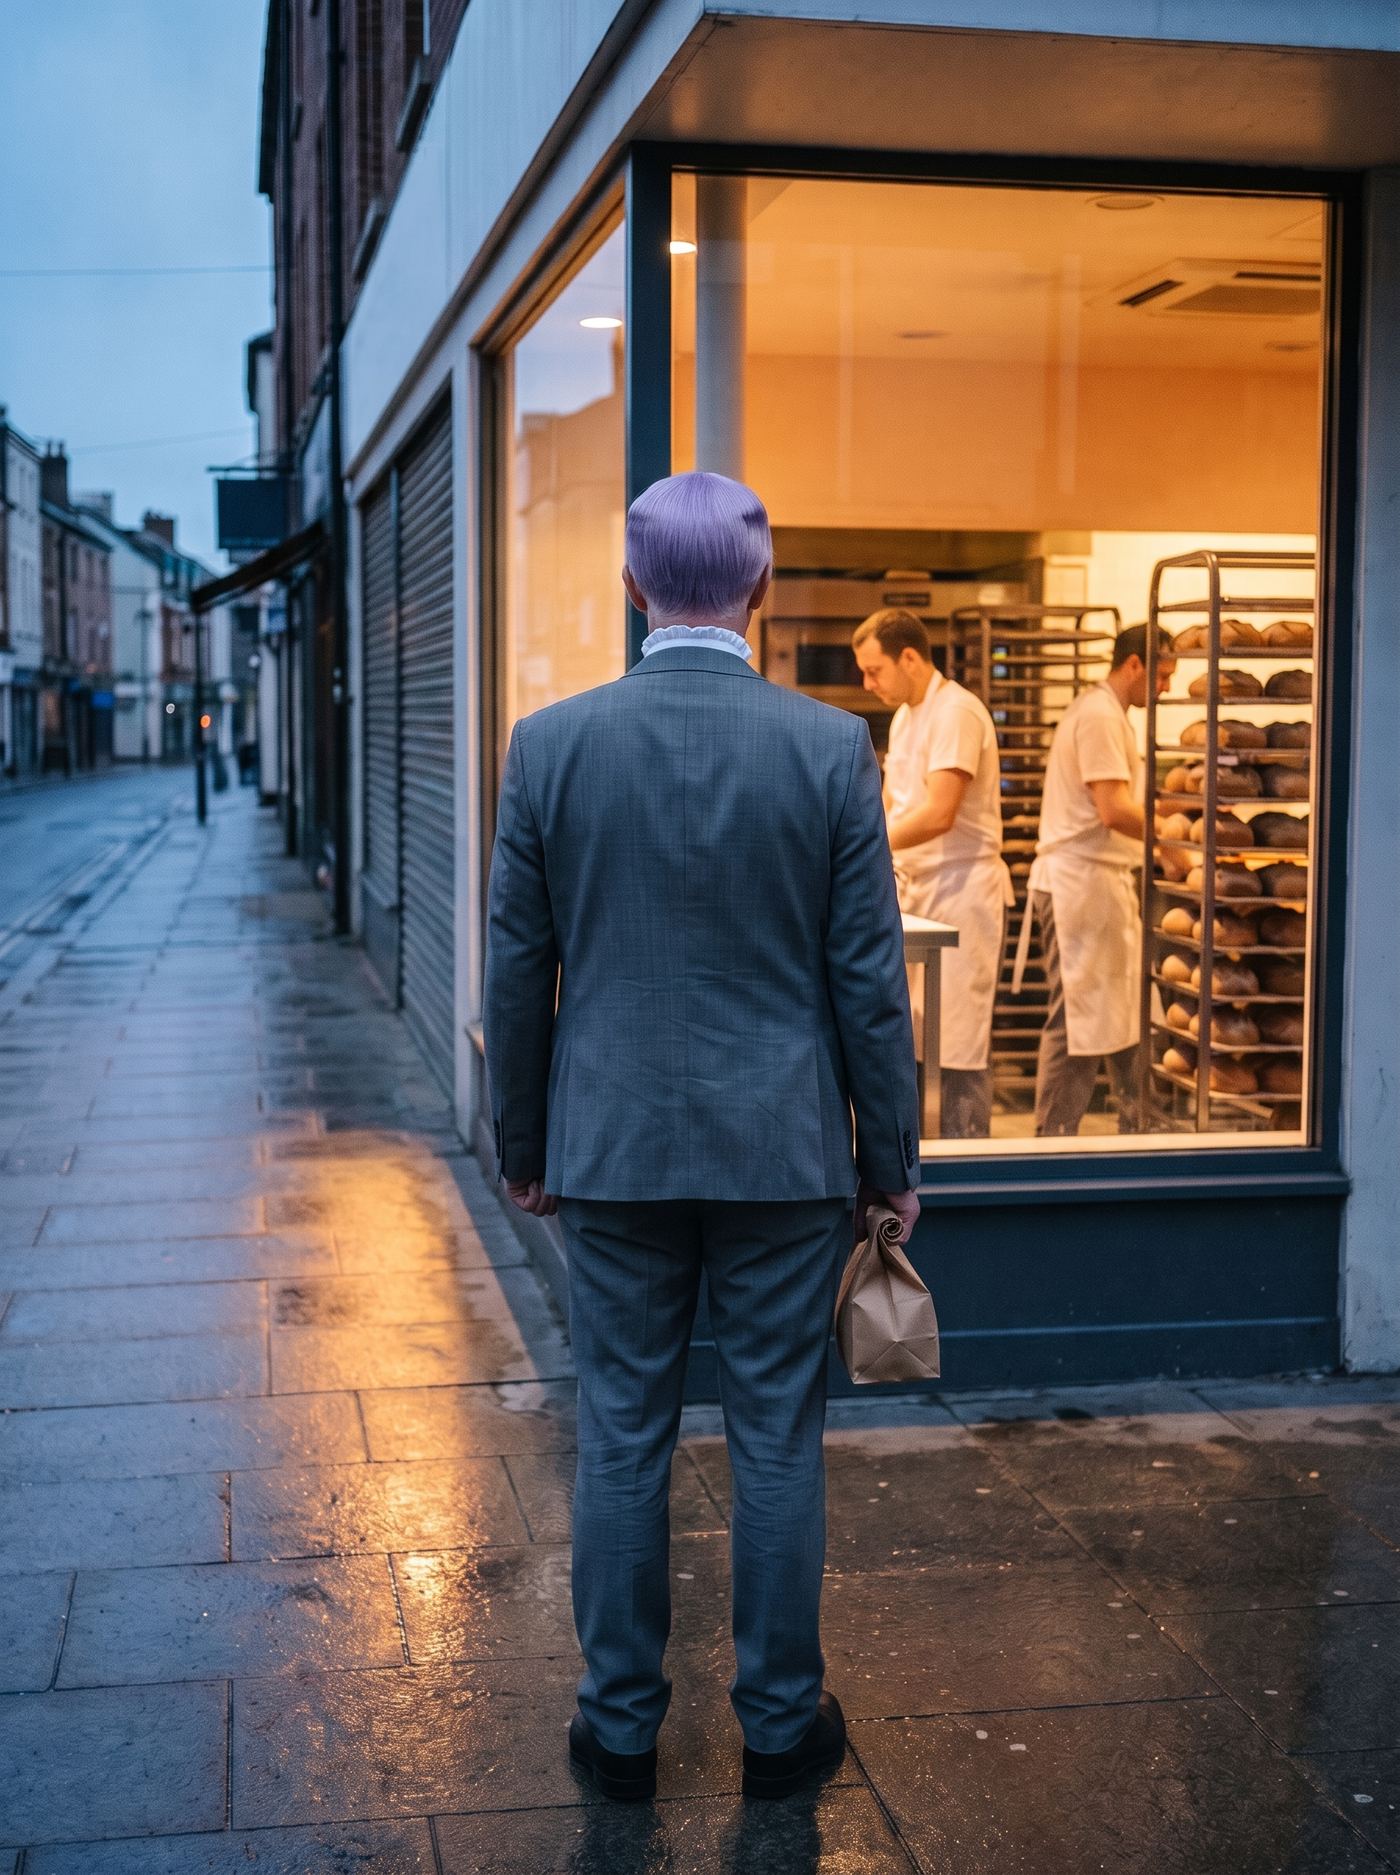
In the photograph the rise has already happened and the door is still locked. The bakery is lit and working, the racks are loaded, the loaves went up in the dark while the street was empty, and the man with the bag is on the pavement outside the glass at the hour when there is nothing left to do but look at it. The ground is the street's own pre-dawn blue; the pigment is the window.
The artifact
A baker who sets dough down at night clips a docket to the rack so that whoever opens in the morning can read what happened while nobody was in the room. Thursday's market filled one in. The index was set down at 7,551.81 and found at the bell at 7,631.44, and the whole of the difference — 79.63 points, nine parts in ten of everything the day would be worth — was made in the dark, with the door locked and nobody able to pay for it.
The pale sliver at the top is the part that was still for sale. Three hundred and ninety minutes of American trading, every screen lit, every desk staffed, moved the index 6.32 points. The lowest price anyone was offered all day stood sixty points above the level the argument had started from. This is what a market looks like when the thinking is done somewhere else and the session is only the receipt.
The ledger — what actually happened
| Measure | Close | Change | Marginalia |
|---|---|---|---|
| S&P 500 | 7,637.76 | +85.95 · +1.14% | opened 7,631.44, a gap of +79.63 on Wednesday's close; high 7,646.86 at 15:50, low 7,611.81 at 10:10, full range 35.05 — forty-six hundredths of one percent. The best day since the tariff pause window, and the whole of it delivered before the bell |
| The gap | +79.63 | the difference between Wednesday's close and Thursday's opening print, made while the market was shut. It is 92.65 percent of the entire day's gain. A position held overnight collected it; nobody who traded on Thursday could | |
| The session | +6.32 | open to close, across 390 minutes of regular trading — eight hundredths of one percent. Six and a half hours of a market that had already made up its mind and spent the day confirming that nobody wished to argue | |
| The gap never filled | +60.00 | the lowest print of the entire session, 7,611.81 at ten past ten, still stood sixty points above Wednesday's close of 7,551.81. There was no minute of the day in which yesterday's level could be bought | |
| The first ten minutes | 0.26 | the 9:30 to 9:40 bar reached 7,646.60. The high of the whole session, at ten minutes to four after six hours and twenty minutes of further trading, was 7,646.86 — better by twenty-six hundredths of one point. That opening bar alone drew 24.14 of the day's 35.05-point range, 68.9 percent of it | |
| Drawn by ten past ten | 99.17% | the share of the day's final range already in place forty minutes after the open. Wednesday's page, "Nothing before two", had drawn 24.52 percent by two in the afternoon — the lowest of the 133 sessions in the complete intraday record, where the median session stands at 100.00. Back to back: the slowest day in the record to make up its mind, then a day that arrived with its mind made up | |
| Technology | +2.26% | best of the eleven sectors by 1.16 points. Intel +7.62 on the Lip-Bu Tan memory remarks, AMD +6.31, Micron +5.50, the semiconductor fund +2.76, Nvidia +2.57, Broadcom +2.29. On Wednesday technology was also the best sector, at +0.13 | |
| The telephone companies | −5.57 | T-Mobile −5.57, Comcast −3.41, Verizon −2.86, AT&T −1.84, Charter −1.13, with Disney −1.55 and Netflix −1.45 alongside them. This is why communication services was the worst of the eleven sectors at −0.59 while two of its largest holdings rose: Meta +1.39 and Alphabet +1.32. The published explanation for T-Mobile is rate sensitivity on a heavily indebted balance sheet, plus a third-quarter call set for 28 October carrying no new guidance. That explanation is incomplete and this page says so: utilities are equally debt-laden and rose 0.86 percent on the same session, and long Treasuries rallied | |
| Financials | −0.10% | the second of the day's two red sectors, and red without the banks being red: Goldman Sachs +1.40 after falling 3.91 on Wednesday, Bank of America +0.47, JPMorgan +0.09, the regional bank fund +0.03. The decline came from somewhere other than the four bank measures checked here and this page does not claim to know where. Nine of eleven sectors closed green; the spread best to worst was 2.85 points | |
| Volatility | 15.44 | from 17.71, down 2.27 points or 12.82 percent — and below the 15.84 of Friday 11 September, the figure this site corrected that page to on Wednesday. Whatever arrived for the meeting left the morning after it | |
| The ten-year Treasury | 4.951% | back under five, from the 5.008 this site published on Wednesday — about six basis points lower. The twenty-year-plus Treasury fund rose 1.11 percent. The Federal Reserve raised rates on Wednesday and the long end rallied on Thursday, which is the same bargain Wednesday's page recorded the long end accepting, now being paid | |
| Gold and silver | +1.67 / +3.35 | silver was the largest move on this page after Intel. Gold, silver, long bonds and equities all rose together on the day after a rate rise, which is a market pricing credibility rather than tightness. The bitcoin fund +0.64; the homebuilders +0.28 | |
| Crude | −1.29% | the Brent fund fell 1.29 and the broad WTI fund 0.53, a second day of easing after Wednesday's pipeline sentence. Energy still finished green at +0.68, having been the worst of the eleven on Wednesday at −2.84 | |
| The other indexes | +1.72 / +0.59 | the Nasdaq 100 +1.72, the S&P 500 +1.14, the Dow +0.59, the Russell 2000 +0.52 — ranked cleanly by how much silicon each one holds. Wednesday the Dow fell 631 points while the Nasdaq Composite fell three |
Sources
- Robinhood market-data feed — SPX 10-minute bars across the full session and the settled close; the VIX index series; quotes and official 16 September closes for the eleven sector funds, SPY, QQQ, DIA, IWM, SMH, KRE, XHB, GLD, SLV, TLT, IBIT, USO, BNO and every individual name on this page. All percentages here, including every sector, are computed from the feed. Pulled 2026-09-17 after the close, fully settled
- CNBC — "Treasury yields move lower after Fed kicks off hiking cycle" — https://www.cnbc.com/2026/09/17/treasury-yields-move-lower-after-fed-kicks-off-hiking-cycle.html
- Barchart — "Stocks Supported by Chip Stock Strength and Lower Bond Yields" (the Lip-Bu Tan memory-demand remarks and the chip rally)
- Investing.com — "Why is T-Mobile stock sliding today?" (the rate-sensitivity and guidance explanation this page reports and then questions)
- This site's own 2026-09-16 page — Wednesday's close, the 24.52 percent figure and the 133-session intraday record, the 5.008 ten-year, the 17.71 VIX and Goldman's −3.91