Stronger than expected
S&P 500 7,706.03 · −58.61 · −0.75%
At a quarter to ten on Wednesday morning, S&P Global reported that American business had just had its strongest month since July 2021. Its survey of purchasing managers came in at 58.4 where economists had expected 55.3, factories at 57.0 and services at 58.7. That was the good news, and the market treated it as a bill. An economy running that hot is one the Federal Reserve, which raised rates only a week ago, may have to raise them on again, and a Fed governor said further adjustments were likely to be needed. The price of borrowing rose to meet him. The ten-year Treasury yield went to its highest level since 2007, and at one o'clock the Treasury sold $70 billion of five-year notes and had to pay 5.033 percent to do it. The S&P 500 had opened at 7,761.94. That turned out to be the best price of the day. Not one minute of the session closed above Tuesday's finish, and the index ended at 7,706.03, down 58.61.
The day's protagonist
McDonald's MCD
Move: −4.81% to $238.32, its lowest close since October 2022
McDonald's held an investor day on Wednesday, and in the course of it the chief executive, Chris Kempczinski, said something that sat awkwardly beside the morning's survey: that customer traffic across the restaurant industry in the company's key markets would be flat, while inflation continued to accelerate. The company set out an $8.5 billion programme to remodel restaurants, improve the menu and upgrade its ordering technology, about $5 billion of it through 2030 in rent relief and capital support for its franchisees. The shares opened at $250.29, fell as far as $234.03, down 6.52 percent, and closed at $238.32, down 4.81, on 16.6 million shares, more than three times Tuesday's volume. It was the company's largest one-day fall since April 2025 and its lowest close since 12 October 2022, and it took $8.51 billion off its market value. It is worth setting the day's two reports side by side, because both are measurements and they point in opposite directions. At a quarter to ten the purchasing managers of the United States said business was the strongest it had been in five years. By the afternoon the largest restaurant chain in the world had said that the number of people coming through its doors was not going to grow, and that its costs were. The first is a survey of companies. The second is a count of customers. The lane in the photograph belongs to the second.
The deeper account
There is an old joke in markets that good news is bad news, and on Wednesday it stopped being a joke for a morning. The survey S&P Global publishes each month from purchasing managers — the people inside companies who order the materials and hire the services, and who are usually the first to know whether business is picking up — came in at 58.4, the highest since July 2021. Anything above 50 means expansion; economists had expected 55.3. For a week-old story about a Federal Reserve that has just raised interest rates for the first time since 2023, and says inflation is not coming down fast enough, that is the wrong kind of strong. A hotter economy is one the Fed may have to cool again, and by the afternoon the reported odds of a second rise in October were about seventy percent. Governor Michael Barr said further adjustments were likely to be needed.
The bond market set the price. The ten-year Treasury yield rose to its highest since 2007 — the wires put its close anywhere from 5.06 to 5.11 percent — and the thirty-year to about 5.37. Then at one o'clock the Treasury auctioned $70 billion of five-year notes, and the buyers who turned up wanted more than the market had been paying a moment earlier: the notes cleared at 5.033 percent, reported as the highest yield at the auction since 2006, with a tail of 3.1 basis points. Foreign and fund buyers took 54.3 percent of the issue where they usually take about 65; the dealers, who are obliged to bid, were left holding 15.8 percent. The S&P 500 was at 7,705.79 at 1:01. At 1:02 it fell 8.64 points in a single minute, and at 1:04 it made its low for the day, 7,694.89.
The shape of the day is simpler than any of that. The index opened at 7,761.94, just under Tuesday's close, and that first print was the highest it traded all day. From there it went down, and it never came back: every one of the session's 390 minutes closed below Tuesday's 7,764.64. On Tuesday this book recorded the index crossing its previous close twenty-five times. On Wednesday it did not cross it once. It is the eleventh session this year whose opening print was its best, and the fifth in September alone — the fourth, the eighth, the ninth, the eighteenth and now the twenty-third — which is a peculiar habit for a market to fall into: to be at its most optimistic at half past nine, and a little less so every hour after.
Almost everything fell with it. Ten of the eleven sectors went down, and the two that trade most like bonds — utilities, down 1.92 percent, and real estate, down 1.55 — did worst, because a company that pays its owners a steady dividend is worth less when a Treasury note pays five percent for nothing. Energy was the one sector up, with oil. The small-company fund fell 1.84 percent; smaller companies borrow at floating rates. Gold fell 1.80 and the bitcoin fund 1.95: the things that pay no interest at all lost ground on the day interest rose. McDonald's, whose chief executive chose the same morning to say that nobody's restaurant traffic was going to grow, fell 4.81 percent to its lowest close in nearly four years.
Technology fell a little less than the rest and not in step. The Nasdaq 100, a day after its first record since June, gave back 0.85 percent; Alphabet fell 3.80 and Micron 2.22; software, of all things, rose 1.26. Meta rose 1.02 percent on the day of its Connect conference, ahead of the evening keynote at which Mark Zuckerberg was to explain how the Muse assistant that had moved the market on Monday and Tuesday would make money. The Dow fell 352.10 points to 51,511.59, and the VIX rose from the year's lowest close, 14.21, to 15.18.
Two honest notes. The survey is S&P Global's flash estimate, the first of two readings each month, and it is revised. And the Treasury figures on this page are the wires', not the feed's: this book's market-data feed carries prices for funds that hold Treasuries but not the yields themselves, and the wires did not agree with one another about where the ten-year closed. The page prints the range and says so. The movement of the long-bond fund, −1.58 percent, is the feed's own number and needs no one's agreement.
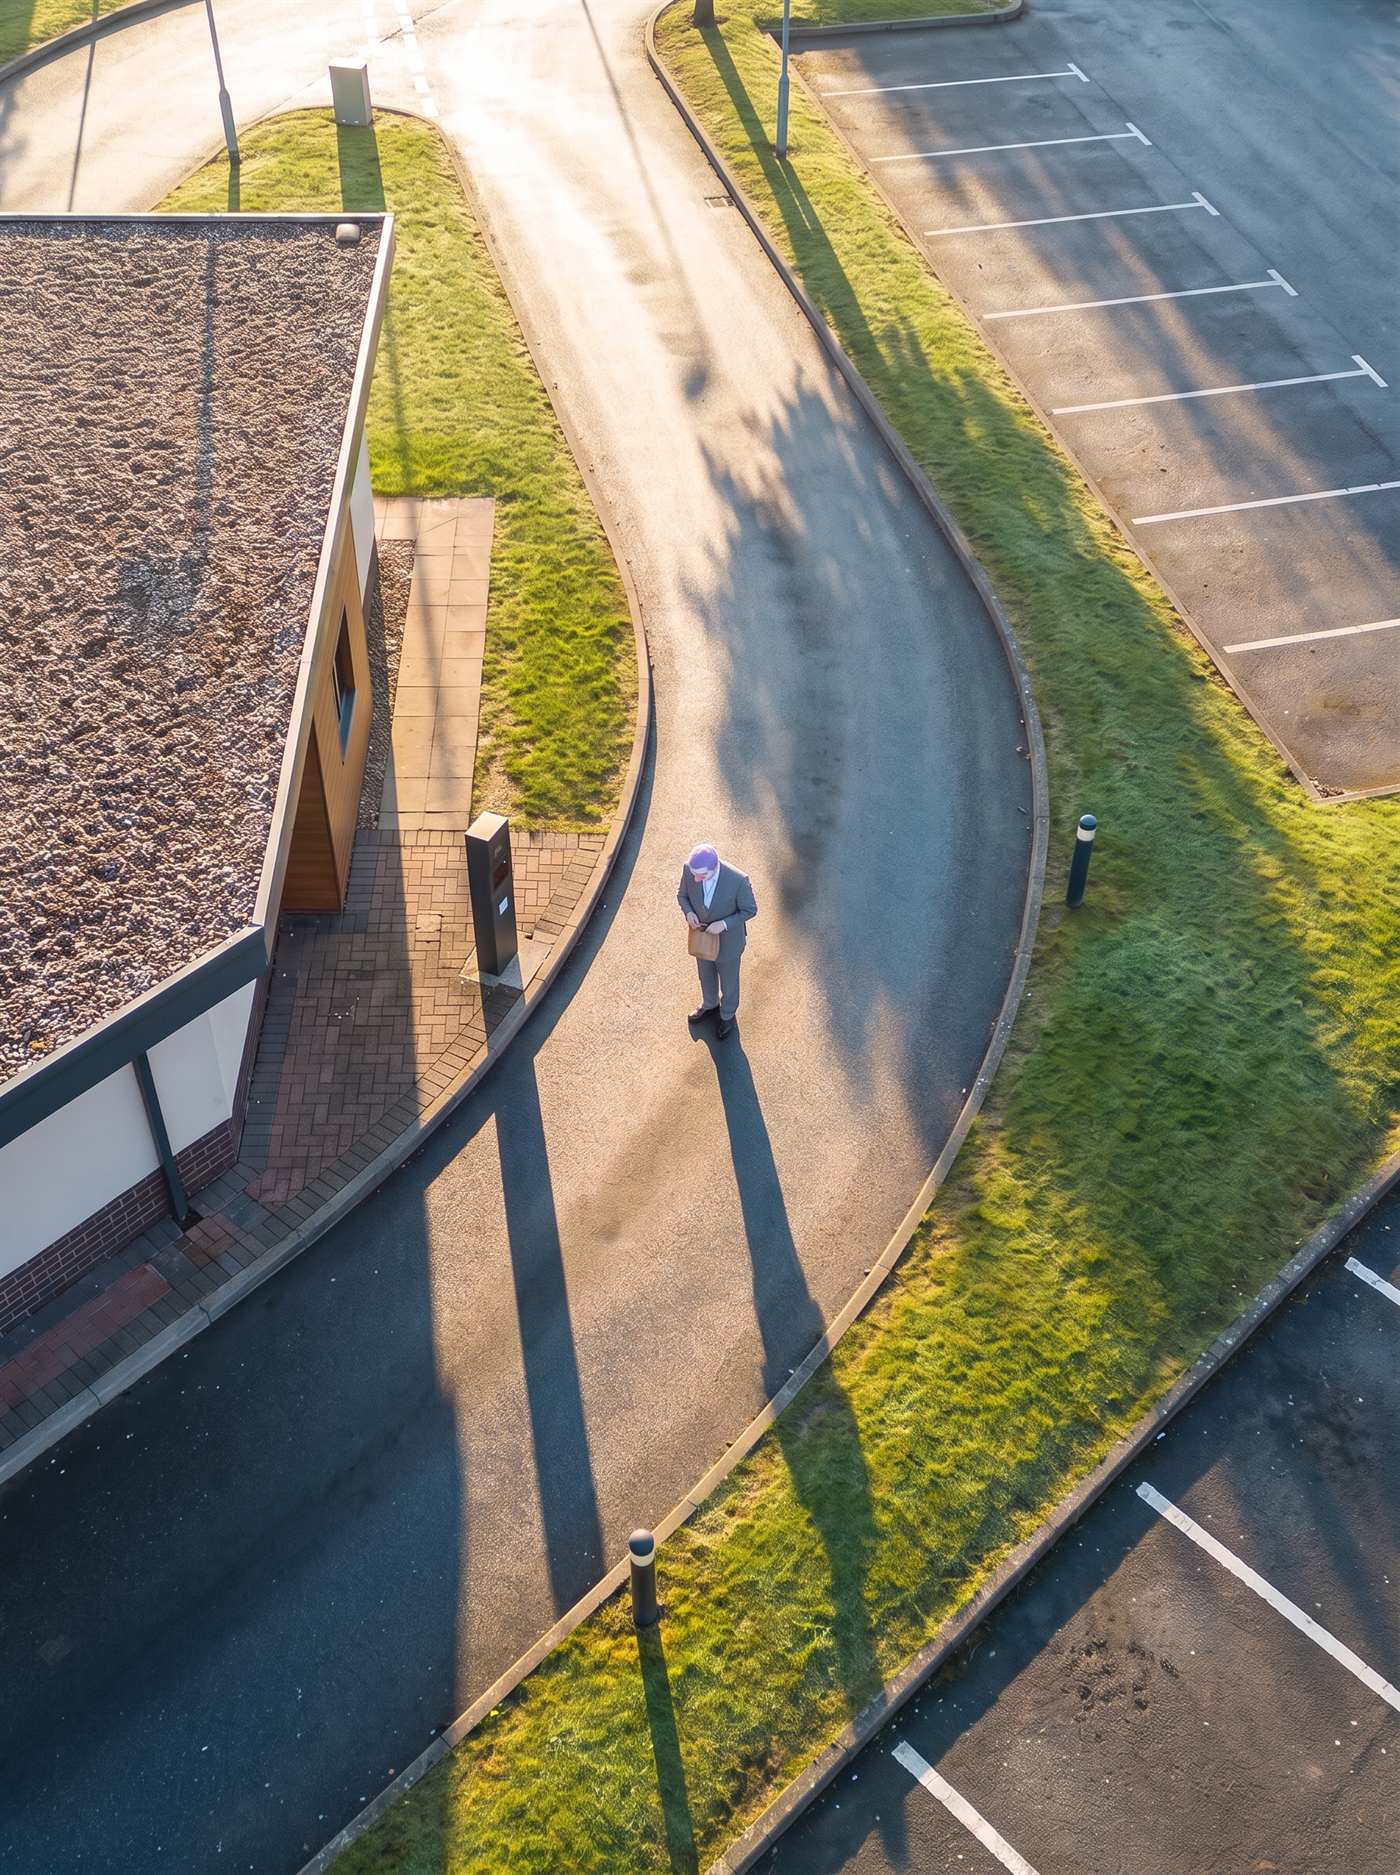
In the photograph it is ten past seven on the same Wednesday, before any of it, and the sun has only just come up over a fast-food restaurant at the edge of a town. The camera is at the top of a light pole. Below it the drive-through lane curves around the building, wet from the night's sprinklers, and there is not one car in it; the car parks beyond are empty. In the middle of the lane, beside the order post, exactly where a driver's window would be, stands a man in a grey suit who has come on foot. His head is bowed over the paper bag in his hands, and his shadow runs a long way back up the lane behind him. For a few minutes the low sun has made everything gold — the dew, the kerbs, the wet asphalt — the way the first price of Wednesday was the best one. By half past nine it will be ordinary light. He is early, as he always is, at the one window in town that was built for somebody who drove.
The artifact
The ledger — what actually happened
| Measure | Close | Change | Marginalia |
|---|---|---|---|
| S&P 500 | 7,706.03 | −58.61 · −0.75% | opened 7,761.94, 2.70 below Tuesday's close, and that first print was the high of the day; low 7,694.89 at 1:04; a range of 67.05, with the close 16.6 percent of the way up it. All 390 minutes of the session closed below Tuesday's 7,764.64. It is the eleventh session of 2026 whose opening print was its best price, and the fifth this September |
| The survey | 58.4 | S&P Global's first estimate of its September composite index of purchasing managers, released at 9:45 — the highest since July 2021, against 55.3 expected and 56.0 in August. Manufacturing 57.0 against 53.7 expected; services 58.7 against 55.8. In the eight minutes after it the S&P 500 went from 7,749.78 to 7,738.41 | |
| The five-year auction | 5.033% | $70 billion of five-year notes sold at one o'clock, reported as the highest yield at the auction since 2006. It tailed by 3.1 basis points; the bid-to-cover was 2.21 against an average of 2.33, indirect bidders took 54.3 percent against an average of 65.2, and dealers were left with 15.8. At 1:02 the index fell 8.64 points in a single minute, the second-largest one-minute fall of the day, and its low came at 1:04 | |
| The ten-year | 2007 high | the highest ten-year Treasury yield since 2007 — the wires printed anything from 5.06 to 5.11 percent at the close, and this page does not choose. The thirty-year touched about 5.37. The long-bond fund fell 1.58 percent and the seven-to-ten-year fund 1.06 | |
| The October meeting | ~70% | the market's reported odds of a second quarter-point rise at the Fed's October meeting, a week after the first rise since 2023. Governor Michael Barr said further adjustments to policy were likely to be needed to bring inflation back to target in time | |
| McDonald's | −4.81% | to 238.32, touching 234.03, its lowest price since October 2022, on the day its chief executive said industry traffic would be flat. KB Home −2.96. Amazon −2.24, Alphabet −3.80. Darden, which reports on Thursday, +0.07 | |
| Eleven sectors, one green | 1 of 11 up | energy +0.96 alone; then industrials −0.10, staples −0.36, technology −0.47, financials −0.47, materials −0.49, health care −0.64, communication services −0.85, consumer discretionary −1.50, real estate −1.55 and utilities −1.92 — the two sectors that trade most like bonds did worst. The equal-weight fund fell 0.70 and the small-company fund 1.84. Software, alone, rose 1.26 | |
| The Nasdaq 100 | −0.85% | 30,470.29, down 262.10, the day after its first record since June. The Composite fell 1.13 percent to 26,936.04 and the Dow 352.10 to 51,511.59, both reconciling exactly with Tuesday as published here. Semiconductors −1.23, Micron −2.22, Nvidia −1.47 | |
| Meta | +1.02% | to 744.10, one of the few large companies to rise, on the day of its Connect conference; it traded as high as 763.90. Mark Zuckerberg's keynote was that evening, after the close | |
| Volatility | 15.18 | from 14.21, the lowest close of the year, up 0.97. The index's insurance got dearer on the day the economy reported itself in the best health in five years | |
| Crude | +3.30% | the broad WTI fund, ending a run of five falls; Brent was reported back above $103 at the settle. Diesel was at a record national average of $6.52 a gallon, and the President backed a ban on diesel exports | |
| Gold | −1.80% | the gold fund, with the bitcoin fund −1.95 — the two things on this page that pay no interest both fell on the day interest went up |
Sources
- Robinhood market-data feed — SPX 1-minute bars across the full session and the settled close from the post-4:00 PM quote; the VIX and Nasdaq 100 index series; SPX daily bars from October 2024 for the opening-print count; quotes and official 22 September closes for the eleven sector funds, RSP, SPY, QQQ, DIA, IWM, SOXX, IGV, KRE, TLT, IEF, GLD, IBIT, USO and every individual name on this page; McDonald's daily closes from January 2020 for its ranks; share counts and volumes from the feed's fundamentals. Every percentage and every dollar figure here is computed from the feed. Pulled 2026-09-24 after the close, fully settled
- Yahoo Finance live blog — "Stock market today: Dow, S&P 500, Nasdaq tumble as 10-year Treasury yield surges to 2007 high" (the flash PMI readings and expectations, Michael Barr, the CME FedWatch odds, the thirty-year) — https://finance.yahoo.com/markets/live/stock-market-today-wednesday-september-23-dow-sp-500-nasdaq-080556640.html
- Investrade — "Market Review: September 23, 2026" (the composite PMI of 58.4, highest since July 2021; Brent; the record diesel average and the export ban) — https://investrade.com/market-review-september-23-2026/
- Helious — "5-Year Treasury Note Auction Results", 23 September 2026 (the high yield, tail, bid-to-cover and bidder shares against their averages) — https://helious.io/news/auc-91282CRN3-2026-09-23/5-year-note-auction-weak
- Seeking Alpha — "U.S. 5-year Treasury note auction pays highest yield since 2006" (headline) — https://seekingalpha.com/news/4646269-us-5-year-treasury-note-auction-pays-highest-yield-since-2006
- Yahoo Finance — "McDonald's shares drop after CEO reveals lackluster growth forecast industrywide as inflation accelerates" (Chris Kempczinski on flat industry traffic; the $8.5 billion programme and the $5 billion for franchisees) — https://finance.yahoo.com/markets/stocks/articles/mcdonald-shares-drop-ceo-reveals-162759471.html
- VistaP Global — "Daily Market Summary - Sept. 23, 2026: Stocks Retreat as Treasury Yields Surge and Inflation Risks Reprice" (the Dow at 51,511.59 and the Composite at 26,936.04) — https://vistapglobal.com/daily-market-summary-sept-23-2026-stocks-retreat-as-treasury-yields-surge-and-inflation-risks-reprice-amwl-amzn-docs-dis-eprx-ionq-mcd-modd-nvda-ser-tsla-wor-ysg/
- This site's own 2026-09-16, 2026-09-18 and 2026-09-22 pages — the rate rise, the opening print of 18 September, and Tuesday's twenty-five crossings and closes