Sixty-three ninety
DOW JONES 63.90 · −0.48 · −0.75% · the floor the twenties were built on
The bottom of a bear market is a number and nothing else. There is no event on this Wednesday, no capitulation to point at, no famous sentence spoken by anybody; there is a market that has been falling for twenty-one months falling three quarters of a percent more, and stopping. The next session closed at 63.91, one hundredth of a point higher, which is the smallest possible way for something to change direction. Everything afterwards — the whole decade, the radio pools, the call money, the shoeshine boys of the anecdote, the peak of 1929 that opens the rest of this archive — is measured up from here.
The day's protagonist
63.90 — no symbol.
Move: the last low — and +496% from it in eight years
The depression of 1920 and 1921 was short, extremely sharp, and almost entirely a matter of prices. Wholesale prices collapsed at a rate not matched before or since, unemployment reached double figures, farm incomes were destroyed in a single season, and the Federal Reserve's post-war tightening — undertaken to unwind the inflation the war had financed — was held long enough to be blamed for most of it. The market's share of that was a fall of 46.6 percent from November 1919, ending at 63.90 on August 24, 1921. Recognition came later and in retrospect, as it always does: the following session added a hundredth of a point, the recovery ran through the autumn, and the advance that began at this close carried the average to 381.17 by September 1929, a rise of very nearly six times. This is the floor under the decade that this archive's original first page stands on top of.
The deeper account
The 1920–21 deflation remains the sharpest general fall in prices in the American record. It is short enough, and was left alone enough, that it is still argued over as evidence for opposite conclusions about what governments should do in a slump.
This page and the one before it are a matched pair: the same twenty-one months, seen from the top and from the bottom. Neither day was reported as significant. Both are, now, only because of where the other one is.
The archive's original opening page — September 3, 1929, the record close of 381.17 on the hottest day of the year — is the far end of the advance that begins here. Between this Wednesday and that Tuesday there is no interruption worth the name.
A hundredth of a point is not a signal. It is what a signal looks like at the time.
The artifact
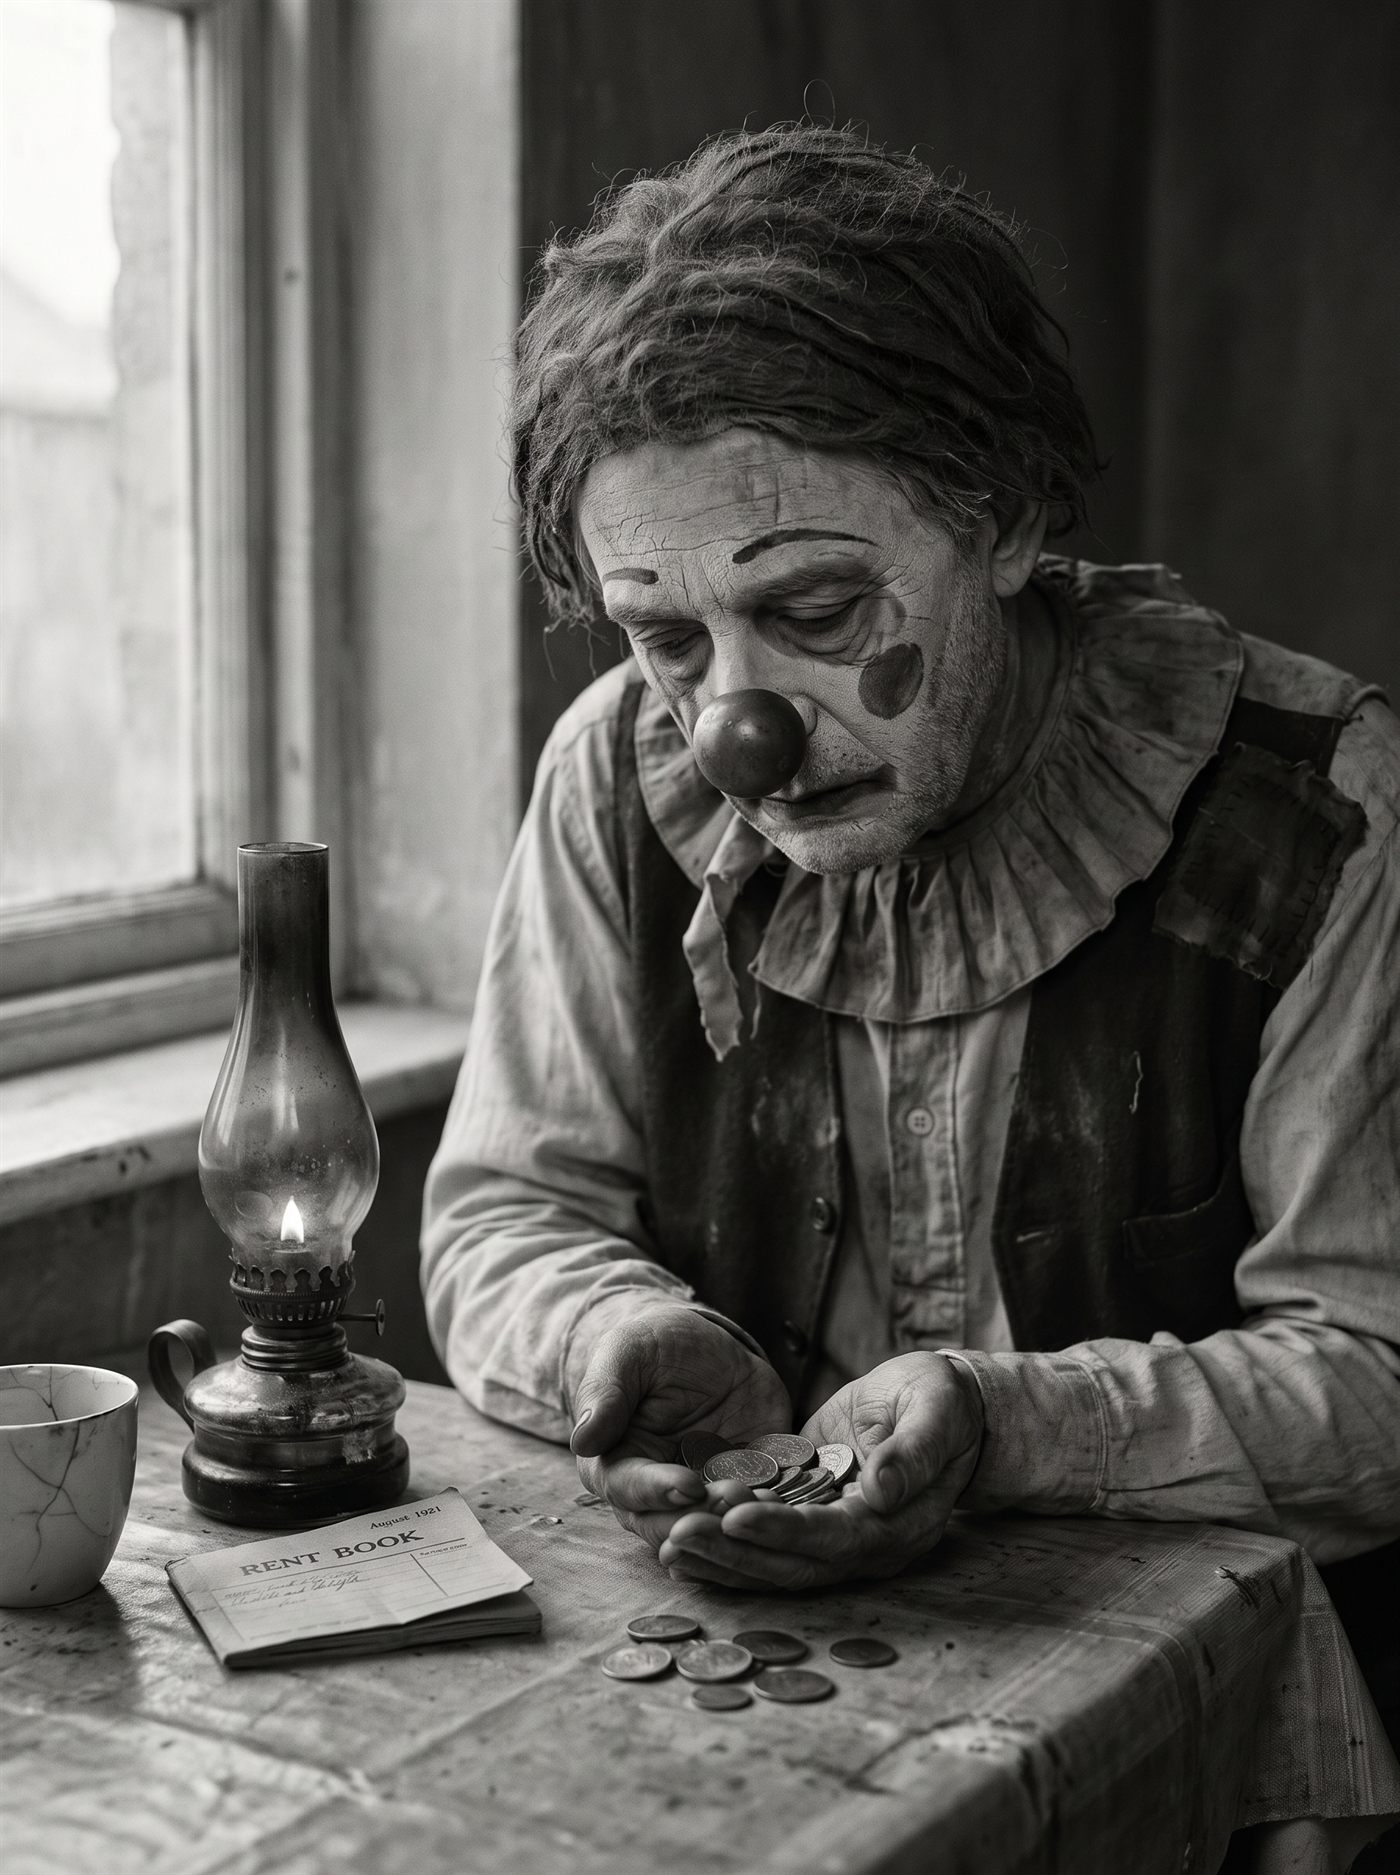
The bottom of a bear market has no ceremony and, for most people, no visible connection to their own week. What the deflation of 1920 and 1921 did was collapse prices faster than anything else could adjust: wholesale prices fell at a rate not matched before or since, farm incomes were destroyed in a season, unemployment reached double figures, and a household could find its income falling while its fixed obligations did not. On August 24, 1921 the Dow closed at 63.90, down 46.6 percent from November 1919. The next session it closed at 63.91 — one hundredth of a point higher, which is what the beginning of the 1920s looked like at the time. From that close the average rose very nearly six-fold in eight years, to 381.17. The rent book is the archive's own; the closing figures are the record's.
Read the page
Printed text is shown plain; the tenant's entries are shown in script.
RENT BOOK · TO BE PRODUCED ON DEMAND — August 1921
- week ending august 6 — due 6.00 · paid 6.00 · arrears —
- week ending august 13 — due 6.00 · paid 4.00 · arrears 2.00
- week ending august 20 — due 6.00 · paid 3.50 · arrears 4.50
- week ending august 27 — due 6.00 · paid and arrears left blank
- TENANT'S HAND: counted it twice. it is the same both times.
- Wages in this city fell faster than the rent did.
- the industrials closed at 63.90 on the 24th — it is the last low. NOTHING HERE RECORDS THAT.
August 24, 1921 was the closing low of the 1920–21 bear market at 63.90, down 46.6 percent from the post-war peak of 119.62 on November 3, 1919. The following session closed at 63.91. The advance that began here carried the Dow to 381.17 by September 3, 1929 — a rise of very nearly six times, and the whole of the decade this archive opens onto.
The ledger — what actually happened
| Measure | Close | Change | Marginalia |
|---|---|---|---|
| Dow Jones | 63.90 | −0.48 · −0.75% | the closing low of the 1920–21 bear market |
| From the 1919 top | −46.6% | 119.62 on November 3, 1919 → 63.90 — twenty-one months, and the previous page on this shelf | |
| The next session | 63.91 | one hundredth of a point — the entire visible evidence of a turn, on the day | |
| To September 1929 | +496% | 63.90 → 381.17 — the whole of the twenties, measured from this Wednesday |
Sources
- MeasuringWorth — Daily Closing Values of the Dow Jones Average (August 20–27, 1921, queried directly; 63.90 on the 24th, 63.91 on the 25th) — https://www.measuringworth.com/datasets/DJA/
- The Depression of 1920–21 — the scale of the deflation, the Federal Reserve's role, and the recovery from the August 1921 trough
- The advance from 63.90 (August 24, 1921) to 381.17 (September 3, 1929), computed from the daily series above