Effective immediately
S&P 500 7,683.69 · −59.72 · −0.77%
Before the market opened on Monday, MongoDB said that its chief executive, CJ Desai, had stepped down, effective immediately, to take a senior job at Meta, and that the man who had run the company before him, Dev Ittycheria, was back in charge, also effective immediately. Its shares fell 18.46 percent. The S&P 500 had a weekend of its own to answer for — the President had turned down Iran's proposal for a seven-day ceasefire — and it opened 21.71 points below Friday's close. At 12:16 it began to climb, and the wires put the climb down to reports that the President was open to easing sanctions on Iran: in twelve minutes it rose 40.01 points, to 7,724.15. That was the high of the day, and it was still 19.26 short of Friday. By four o'clock the whole of it was gone. The index closed at 7,683.69, down 59.72, forty-five hundredths of a point below where it had stood in the minute before the climb began, and not one of the day's 390 minutes traded above Friday's close.
The day's protagonist
MongoDB MDB
Move: −18.46% to $334.68, having touched exactly $300.00
MongoDB makes a database that a great many modern applications keep their records in. Dev Ittycheria ran it for eleven years, from 2014 to 2025, and in that time its annual revenue went from about $35 million to more than $2.3 billion. His successor, CJ Desai, started on 10 November last year. On Monday morning the company said that Desai had stepped down as president and chief executive, effective immediately, to take a senior role at Meta — as its chief enterprise platform officer, reporting to Mark Zuckerberg and running a new unit called Meta Enterprise Platform — and that the board had appointed Ittycheria interim president and chief executive, also effective immediately. It said the departure was not the result of any disagreement, reaffirmed its guidance for the quarter and the year, and hired a search firm. Its investor day, at the Nasdaq MarketSite, was the next morning. The shares, $410.44 on Friday, opened at $311.35 and in the first ten minutes touched exactly $300.00, down 26.91 percent. Then they climbed for most of the day, and closed at $334.68: down 18.46 percent, $6.10 billion of market value, and $34.68 above that round number. 17.9 million shares changed hands, about six times the thirty-day average. Piper Sandler called the reaction overdone. The company that hired him, Meta, fell 4.79 percent the same day — for reasons of its own, by the wires' account.
The deeper account
On Sunday the President told Axios that Iran's proposal for a seven-day ceasefire was not good enough. "They want to make a deal, but it is not the deal that I want to make," he said. "It is what we would have maybe agreed to a year ago. They overplayed their hand." He said he expected more talks this week. On Monday oil and Treasury yields went up and the S&P 500 opened at 7,721.70, 21.71 points below Friday's close of 7,743.41. It spent the morning going down: to 7,697.57 in the first seven minutes, and to 7,666.60 at 10:55, 76.81 below Friday. Brent crude traded above $100 a barrel before it fell back; the ten-year Treasury yield rose to about 5.24 percent, its highest since 2007 — the wires put it anywhere from 5.23 to 5.25 — and the thirty-year to about 5.56, its highest since 2004.
At noon the index stood at 7,684.50. At 12:16 it rose 10.49 points in a single minute, at 12:20 another 9.29, at 12:26 another 11.52, and at 12:27 it touched 7,724.15: 40.01 points above the close of the 12:15 minute, in twelve minutes. The wires tied the move to reports from Axios and from CNN, each citing American officials, that the President was willing to ease sanctions and release frozen Iranian funds in return for concrete steps on Iran's nuclear programme. For three minutes the index traded above its own opening print, by as much as 2.45 points, and one of those minutes closed there. It never came nearer to Friday than 19.26. By 12:42 it was back below 7,700. At 13:11 it jumped again, 21.44 points in one minute, to 7,716.98, and nine minutes later it was at 7,701.31. After that it slid through the afternoon, to 7,677.96 at 15:54, and closed at 7,683.69 — 0.45 below where it had been in the minute before the climb began. The reports were worth forty points for about a quarter of an hour and nothing at four o'clock. That evening, after the close, the President wrote that the Axios story was untrue: "I offered them NOTHING!"
Nvidia said on Monday morning that it was adding $150 billion to its share buyback, leaving $235 billion authorized — the largest single buyback authorization in history, by the press's account. The shares rose 1.68 percent, $93.23 billion of market value, on a day the semiconductor fund fell 2.08: AMD −3.61, Micron −2.61, Intel −5.67. Meta, which had hired MongoDB's chief executive that morning, fell 4.79 percent and lost $91.81 billion, within a billion and a half of what Nvidia gained, for reasons the wires put elsewhere — profit-taking after a 13 percent week, and the cost of its artificial-intelligence building. Boeing fell 6.91 percent on a delay to the certification of the 737 MAX 10; Tesla 3.94 after JPMorgan cut its price target ahead of the quarter's deliveries; Snowflake 2.33 on a $3.5 billion convertible bond. Kodiak Sciences, a biotech company in Palo Alto, nearly trebled — up 177.96 percent — after two of its drugs for wet macular degeneration matched Regeneron's Eylea at one year in a late-stage trial.
The Dow fell 347.11 points to 51,481.51 and the Nasdaq Composite 248.34 to 26,820.38; both reconcile exactly with this book's own Friday closes. For the S&P 500 it was the largest fall in percentage terms since 20 August. Three of the eleven sectors rose — health care, staples and energy, none by more than a third of a percent — and communication services fell 1.58, discretionary 1.41 and financials 1.19. On the New York Stock Exchange falling issues outnumbered rising ones by 3.55 to 1, and the equal-weight fund fell 0.65 percent against the index's 0.77. Gold fell about $164 an ounce. The VIX rose to 16.07 from 14.87. Traders put the chance of a rate rise at the Fed's October meeting at 70.3 percent, up from 57.6 a week earlier.
The close left the index 2.45 points below where it finished August, at 7,686.14: the whole of September's gain, with two sessions of the month to go, was gone. By coincidence, and it is only that, the day's high had stood 2.45 points above its opening print. The index is now 115.30 points, 1.48 percent, below the record close of 13 August. The week brings consumer confidence and job openings on Tuesday, the PCE inflation report on Wednesday and September's payrolls on Friday.
Two honest notes. This page does not know what moved the index at 12:16 or at 13:11; it says what the wires tied the midday move to, and it does not know which of the two reports reached the market first. And the closes shown for individual companies and funds are the feed's daily closing prints; the index close is the settled 7,683.69.
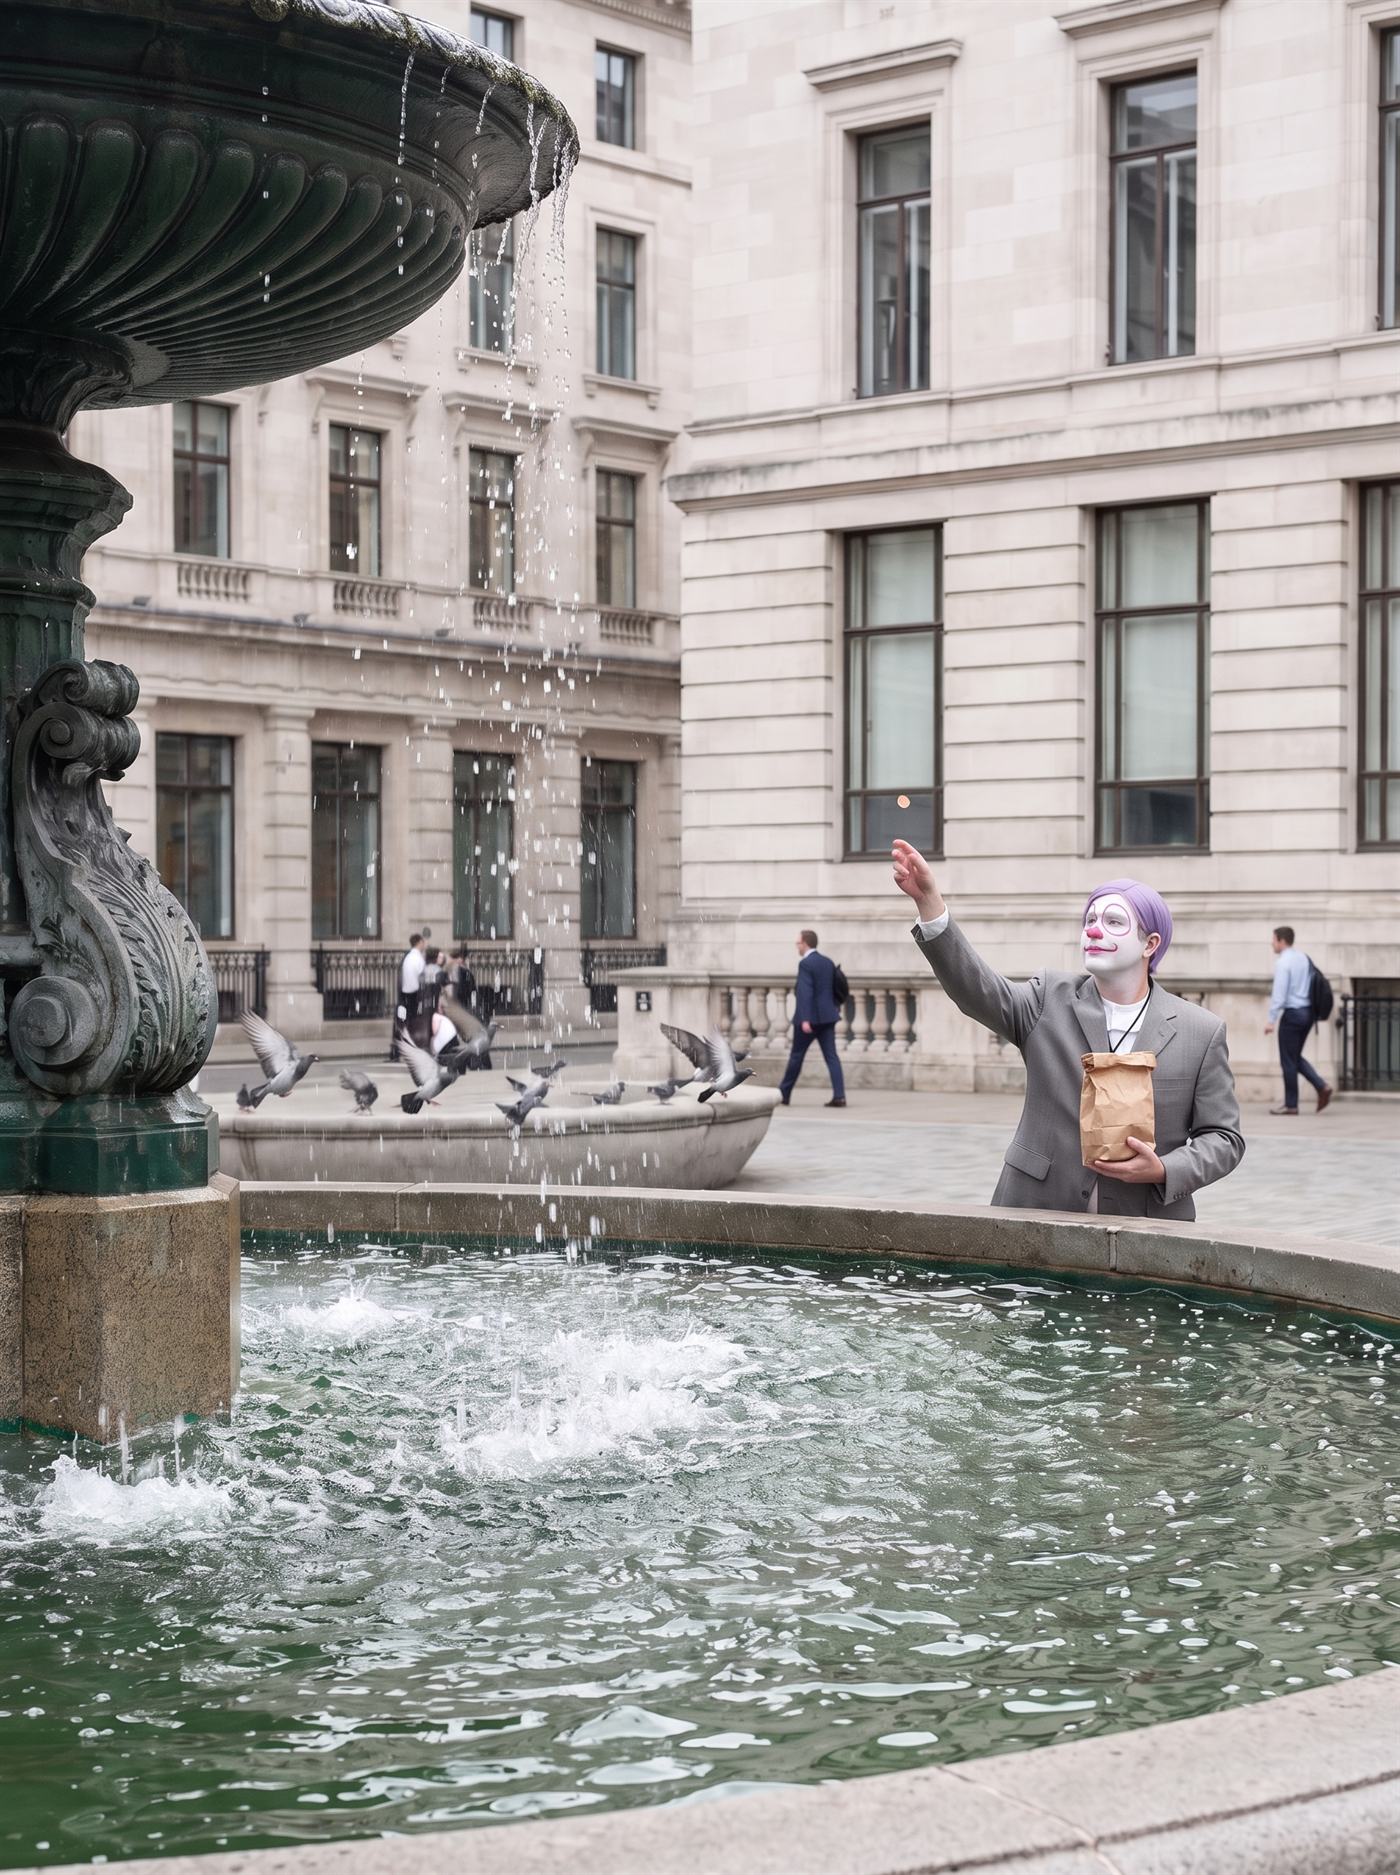
In the photograph it is a quarter past twelve in a stone square among office buildings, and the big bronze fountain has just been switched off. Nothing is coming over the lip of its bowl any more; the last of the water is falling in separate drops, and the basin is still ringing where they land. The pigeons have gone up off the rim. On the far side of the basin the man in the grey suit, who came out at lunchtime with his paper bag to make a wish, has just thrown his coin. It hangs in the air above his open hand, a small copper glint, and he is watching it with his eyes open. He has not noticed that the fountain has stopped. Nobody crossing the square has noticed him.
The artifact
The ledger — what actually happened
| Measure | Close | Change | Marginalia |
|---|---|---|---|
| S&P 500 | 7,683.69 | −59.72 · −0.77% | opened 7,721.70, 21.71 below Friday's close; low 7,666.60 at 10:55, 76.81 below it; high 7,724.15 at 12:27, 2.45 above the opening print and 19.26 below Friday; a range of 57.55, the close 29.7 percent of the way up it. The largest percentage fall since 20 August; 115.30 points, 1.48 percent, below the record close of 13 August |
| Above Friday | 0 min | of the 390 minutes of the session, not one traded above Friday's close of 7,743.41; the nearest the index came was 7,724.15 at 12:27. Three minutes, 12:26 to 12:28, traded above the day's own opening print, and one of them closed there | |
| The reports | +40.01 | from the 12:15 minute's close of 7,684.14 to the 12:27 high, in twelve minutes, as the wires carried reports that the President was open to easing sanctions on Iran. A second jump at 13:11, 21.44 points in one minute, was gone in nine. At the close the index stood 0.45 below its 12:15 level | |
| September | −2.45 | from 7,686.14 at the end of August to 7,683.69: the month's whole gain gone, with two sessions left in it | |
| MongoDB | −18.46% | to 334.68 from 410.44; opened 311.35, touched exactly 300.00 in the first ten minutes and closed 34.68 above it. $6.10bn of market value; 17.9 million shares, about six times the thirty-day average | |
| Nvidia | +1.68% | to 228.86, $93.23bn of market value, after adding $150bn to its share buyback, $235bn authorized in all; it touched 233.21, up 3.62 percent, in the first ten minutes. The semiconductor fund fell 2.08: AMD −3.61, Micron −2.61, Intel −5.67 | |
| Meta | −4.79% | to 715.62, $91.81bn, on the morning it hired MongoDB's chief executive; the wires put the fall down to profit-taking after the previous week's rally and the cost of its AI spending | |
| Kodiak Sciences | +177.96% | to 89.92 from 32.35, after two of its drugs for wet macular degeneration matched Regeneron's Eylea at a year in its DAYBREAK trial; as high as 95.77 | |
| Boeing | −6.91% | to 184.39, on a delay to the certification of the 737 MAX 10 | |
| Eleven sectors, three green | 3 of 11 up | health care +0.33, staples +0.27, energy +0.10; then real estate −0.51, utilities −0.66, materials −0.66, technology −0.89, industrials −0.97, financials −1.19, discretionary −1.41 and communication services −1.58. The equal-weight fund fell 0.65 against the index's 0.77. On the New York Stock Exchange falling issues outnumbered rising ones 3.55 to 1 | |
| The ten-year | 5.24% | about, its highest since 2007 — the wires put it between 5.23 and 5.25; the thirty-year about 5.56 percent, its highest since 2004. The long-bond fund fell 0.88 percent. Traders put the chance of a rate rise at the Fed's October meeting at 70.3 percent, from 57.6 a week before | |
| Gold | −3.94% | the gold fund, as the metal fell about $164 an ounce, to about $4,121 | |
| Crude | +1.13% | the WTI fund. Oil jumped more than $3 in the morning on the rejected ceasefire, Brent above $100, and gave most of it back | |
| Volatility | 16.07 | from 14.87, up 1.20 |
Sources
- Robinhood market-data feed — SPX 1-minute bars across the full session and the settled close from the post-4:00 PM quote; SPX daily bars for 2026 for the month, the record and the largest fall since 20 August; the VIX index series; daily bars for 25 and 28 September for the eleven sector funds, RSP, SPY, QQQ, DIA, IWM, SOXX, IGV, TLT, IEF, USO, GLD and every company on this page; MongoDB, Nvidia, Meta and Boeing 10-minute bars; share counts and volumes from the feed's fundamentals. Every percentage and every dollar figure here is computed from the feed. Pulled 2026-09-29
- Reuters via Investing.com — "Stocks fall as higher oil prices, Treasury yields weigh" (the closes of the Dow and the Composite, the largest fall since 20 August, Boeing, Tesla and Nvidia, NYSE breadth of 3.55 to 1, and the October odds of 70.3 percent against 57.6) — https://www.investing.com/news/economy-news/wall-st-futures-drop-as-oil-spikes-after-trump-rejects-iran-peace-proposal-4919715
- Yahoo Finance live blog — "Stock market today: Dow, S&P 500, Nasdaq fall as Treasury yields continue to climb" (the ten-year at 5.24 to 5.25 percent and the thirty-year at 5.56 to 5.57, their highest since 2007 and 2004; oil above $100; Snowflake's offering) — https://finance.yahoo.com/markets/live/stock-market-today-monday-september-28-dow-sp-500-nasdaq-080420627.html
- investingLive — "Americas market news wrap: Oil prices bounce around on Iran headlines, yields rise" (the ten-year at 5.23 percent, oil up more than $3 early, gold down $164 to $4,121) — https://investinglive.com/news/investinglive-americas-market-news-wrap-oil-prices-bounce-around-on-iran-headlines-yields-rise/
- Yahoo News — "Trump expects more talks after rejecting latest Iranian proposal" (the President's words to Axios on Sunday) — https://www.yahoo.com/news/politics/articles/trump-expects-more-talks-rejecting-115840592.html
- National Security Journal — "Donald Trump Just Denied Offering Iran Sanctions Relief or Giving Back Frozen Assets" (the Axios and CNN reports and the President's post on Monday) — https://nationalsecurityjournal.org/donald-trump-just-denied-offering-iran-sanctions-relief-or-giving-back-frozen-assets/
- MongoDB — "MongoDB Announces CEO Transition" (effective immediately, twice; Ittycheria's eleven years and the revenue; the reaffirmed guidance; the search; the investor day) — https://www.mongodb.com/company/newsroom/press-releases/mongodb-announces-ceo-transition
- Reuters via KSL — "Meta taps MongoDB CEO Desai to lead new enterprise AI platform" (chief enterprise platform officer, reporting to Zuckerberg, Meta Enterprise Platform; Piper Sandler) — https://www.ksl.com/article/51629464/meta-taps-mongodb-ceo-desai-to-lead-new-enterprise-ai-platform
- Yahoo Finance — "Meta Poaches MongoDB CEO 'Effective Immediately'" (Desai's start on 10 November 2025; not due to any disagreement) — https://finance.yahoo.com/markets/stocks/articles/meta-poaches-mongodb-ceo-effective-131452186.html
- GV Wire — "Nvidia Adds $150 Billion to Massive Stock Buyback, the Largest Ever" ($150 billion added, $235 billion authorized) — https://gvwire.com/2026/09/28/nvidia-adds-150-billion-to-massive-stock-buyback-the-largest-ever/
- TipRanks — "Why Meta, Intel, and Bloom Energy Stocks Are Down Today" (profit-taking after last week's 13 percent rally; the capital spending) — https://www.tipranks.com/news/why-meta-intel-and-bloom-energy-stocks-are-down-today-and-what-analysts-see-next-sep-28
- BioSpace — "Kodiak Sciences' stock soars 166% after 2 assets match Eylea in Phase 3 trial" (DAYBREAK, zenkuda and tabirafusp-ted against aflibercept) — https://www.biospace.com/drug-development/kodiak-sciences-stock-soars-166-after-2-assets-match-eylea-in-phase-3-trial
- This site's own 2026-08-31 and 2026-09-25 pages — the close at the end of August, and Friday's closes for the index, the Dow and the Composite